AIRSEA II / INSURANCE BROKERAGE
Insurance for
exceptional assets.
Insurance brokerage for private aircraft, yachts and boats, luxury cars, and high-value homes. Start with a conversation about what you own, how you use it, and what you need your coverage to do.
Speak directly with Joe Rizzo, licensed insurance broker and owner of AIRSEA II.
Talk insurance with Joe ↗What would you like to discuss?
POMPANO BEACH, FLORIDA · 617-962-4500
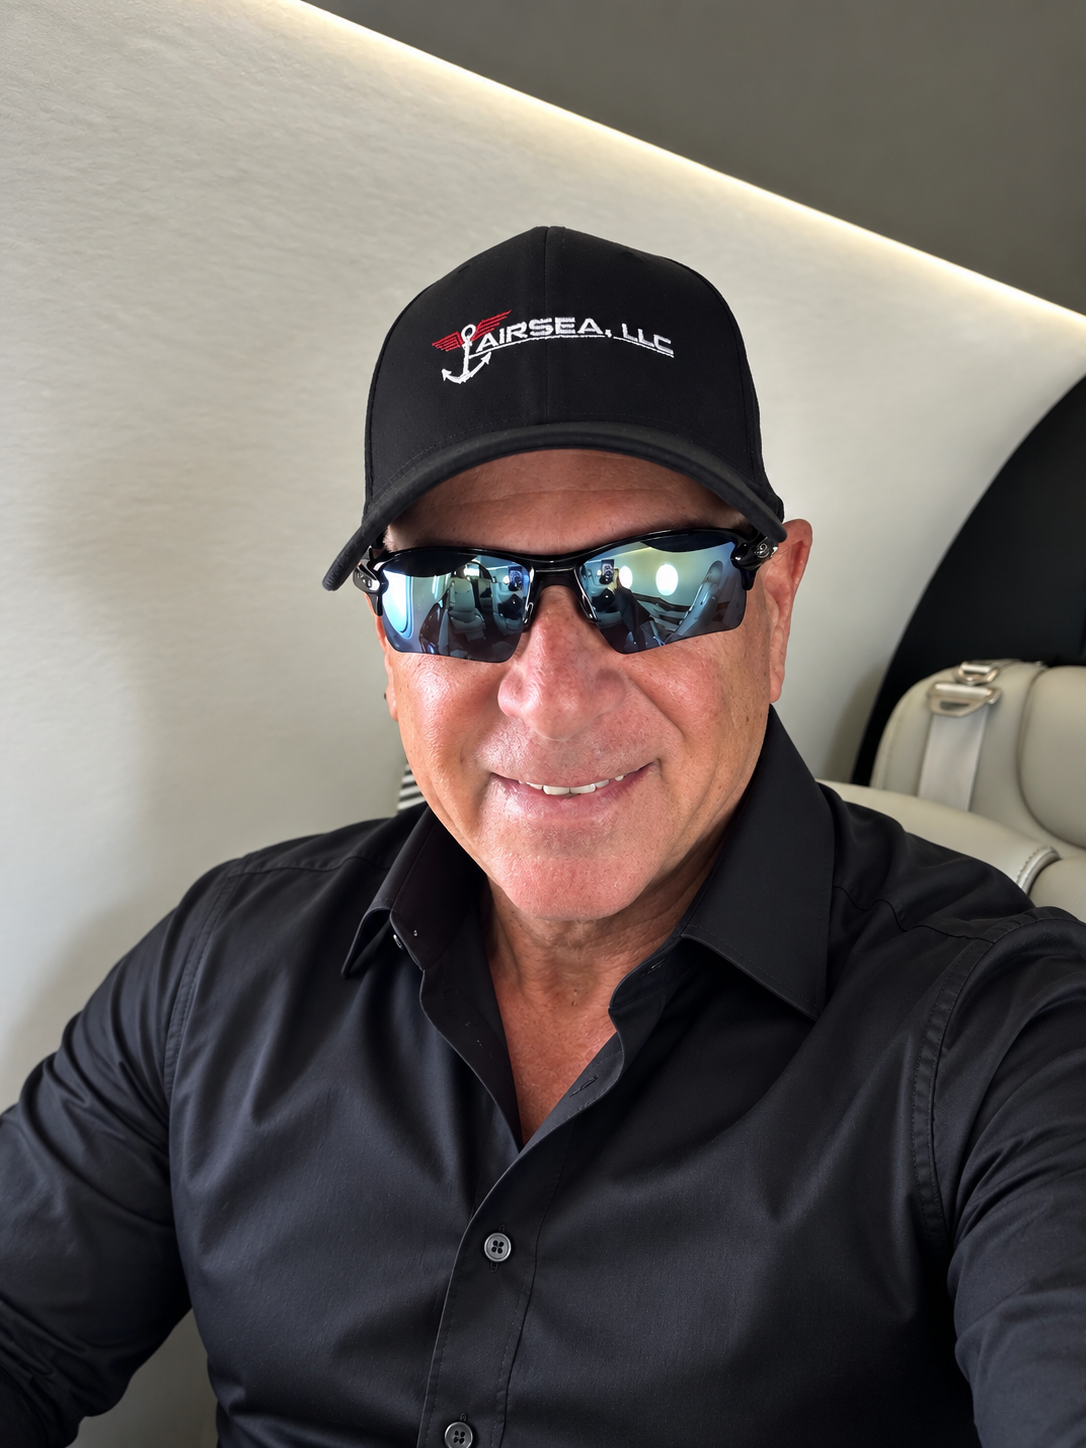
JOE RIZZO / OWNER, AIRSEA II / LICENSED INSURANCE BROKER
WHY WORK WITH JOE
Your broker should understand
what you own.
Joe Rizzo brings an asset owner's perspective to insurance. His work at AIRSEA II includes acquiring, enhancing and remarketing business jets, alongside boat and yacht sales. Aircraft condition, maintenance records, upgrades and ownership costs are part of that work.
That experience helps Joe look beyond a purchase price. He can help you review your priorities, make sense of the coverage questions and identify what needs attention before a purchase or renewal. Changes in use, ownership or value belong in that review.
You also have direct access to the owner of AIRSEA II. Explain the decision ahead and what matters to you, then work through the next steps with Joe. Learn more about Joe's background and AIRSEA II's aviation, marine and insurance services.
FOUR ASSETS. DIFFERENT QUESTIONS.
Start with the details
that change the decision.
Bring Joe a purchase you are considering or coverage you already have. Start with the particular aircraft, vessel, vehicle or property, then review the insurance options available for it.
01 / IN THE AIR
Private aircraft
Discuss the aircraft's insured value, liability needs, ownership and intended use. Include who will fly it, where it will operate, and any management or charter arrangement. Damage to the aircraft and liability to other people are separate coverage questions.
Buying a jet? Bring the insurance discussion into the acquisition process before delivery.
02 / ON THE WATER
Yachts & boats
Talk through the vessel's value, where you keep it and your cruising plans. Ask about total-loss settlement, liability, captain and crew, towing and salvage. A policy's treatment of these items deserves the same attention as its premium.
Mention a planned Bahamas trip, a new captain or charter use before assuming the existing terms fit.
03 / ON THE ROAD
Luxury & collector cars
Tell Joe whether your vehicle is a daily driver, a weekend car or part of a collection. Review total-loss valuation, repair-shop choice and original manufacturer parts. Include every driver, where the car is garaged and how often it is driven.
Ask how a proposed policy treats transport, storage and any track activity. Do not assume they are included.
04 / AT HOME
High-value homes
Discuss the cost to rebuild your home, including custom finishes and recent renovations. Its sale price is not a rebuilding estimate. For a coastal or seasonal property, bring questions about wind coverage, deductibles, flood, time away and rental use.
Keep the conversation specific to the address, construction, occupancy and coverage available there.
Coverage availability depends on the asset, location, use and underwriting. Confirm the services and options available for your situation with Joe.
Useful coverage references:
These references illustrate coverage features to ask about. Availability and terms vary by insurer and policy.
BEFORE YOU COMPARE THE PRICE
Understand the terms.
Then compare the price.
Two quotes can look similar and respond differently to a loss. Bring these four checks to your coverage review.
Discuss your coverage questions ↗THE VALUE
How would a covered loss be settled? Ask whether depreciation applies, how a total loss differs from a repair, and whether recent improvements are reflected.
THE PEOPLE & USE
Who needs to be insured, and which activities are covered? Raise company or trust ownership, hired operators, business use and travel plans where relevant.
THE LIMITS
Compare deductibles, liability limits, exclusions and any required underlying insurance. Ask how policies work together instead of treating each one in isolation.
THE START DATE
Confirm when coverage takes effect and what remains to be completed. A quote or conversation alone is not evidence that insurance is in force.
A SOUTH FLORIDA CONSIDERATION
Give storm and flood
their own discussion.
A home and a boat can face the same storm under very different insurance terms. Review the property's wind or hurricane deductible separately from flood protection. Most homeowners policies do not cover flood damage.
For a vessel, ask about permitted cruising areas, any storm-season restrictions and the preparation the policy requires. If you divide your time between homes or move a boat seasonally, explain that pattern at the start.
Discuss these details while planning your purchase or renewal. Ask about effective dates and any waiting periods before relying on new coverage.
NAIC: understanding flood insurance ↗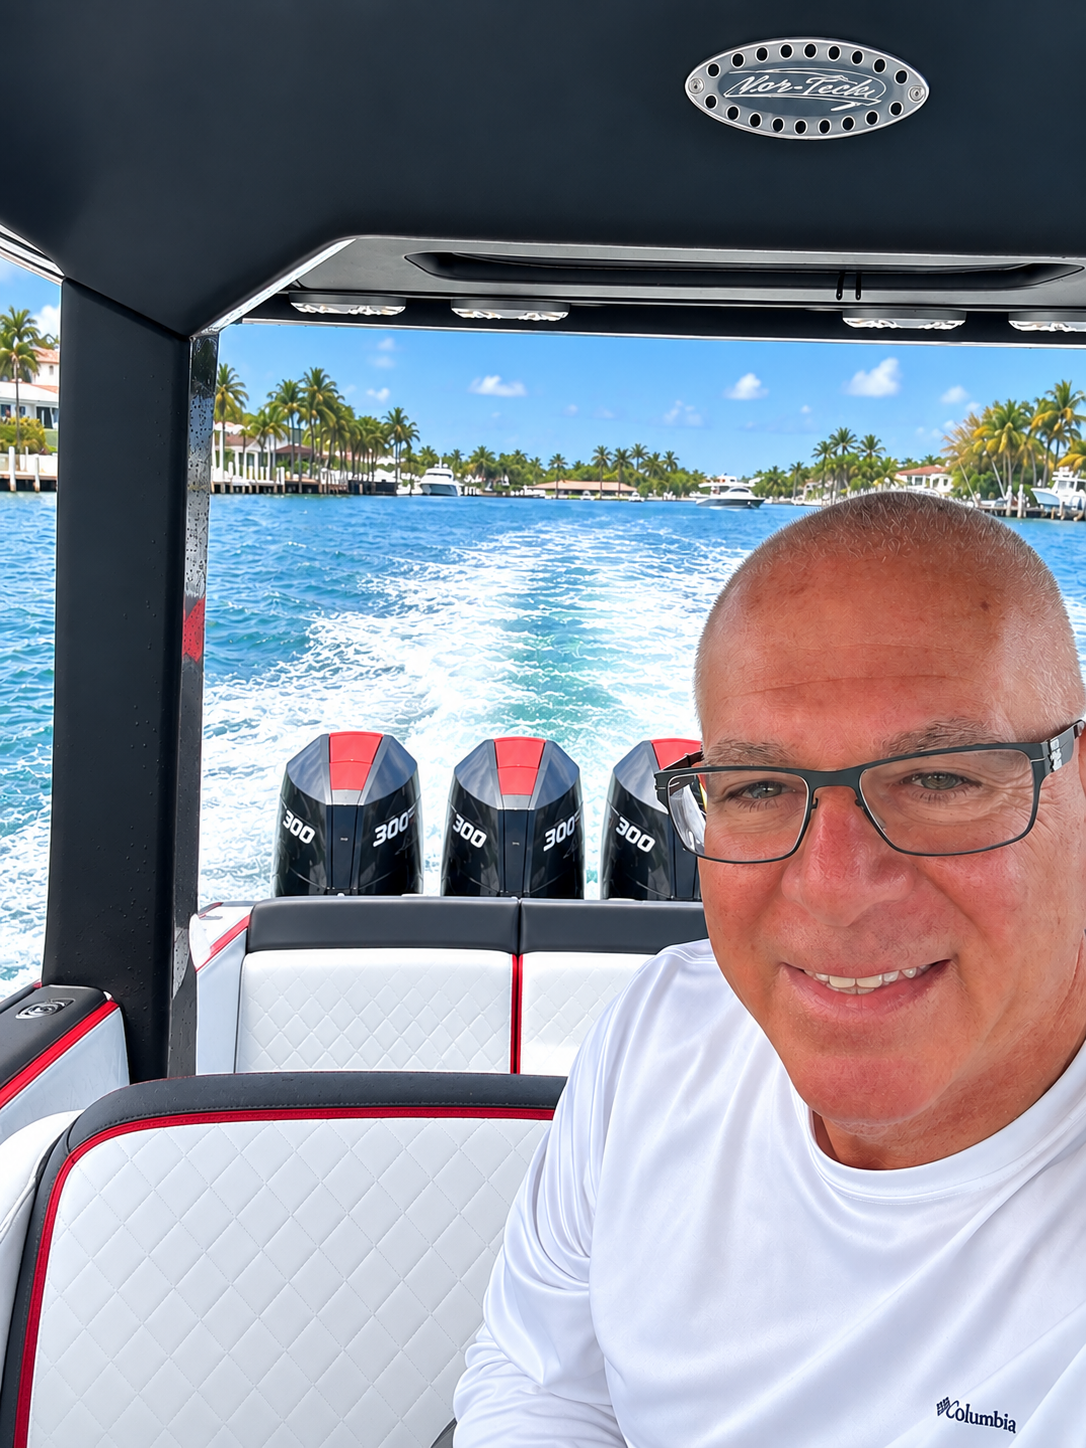
Joe Rizzo on the water in South Florida.
YOUR FIRST CONVERSATION
What to have ready
when you call.
Tell Joe what you want to insure and what prompted the call. You may be buying, approaching renewal, adding another asset or trying to understand an existing policy. Have these details available where they apply.
The asset
Make, model, year or property address; approximate value; significant upgrades; and who owns it.
The current position
Existing policies and declarations, renewal dates, recent claims, and any lender or marina requirements.
What is changing
A closing date, new location, different operator, renovation, planned trip or change in how the asset is used.
QUESTIONS BEFORE YOU CALL
What owners
want to know.
You do not need to know every insurance term before calling. Start with the asset and the question you want answered.
START WITH JOE
Tell Joe what you own.
And what comes next.
A new purchase or an upcoming renewal is a good reason to start. Talk through the asset, your priorities and the insurance questions you need to resolve.
617-962-4500 ↗Insurance is subject to applicable licensing, insurer acceptance and the terms, conditions, limits and exclusions of the issued policy. This page describes topics for discussion and does not bind coverage.